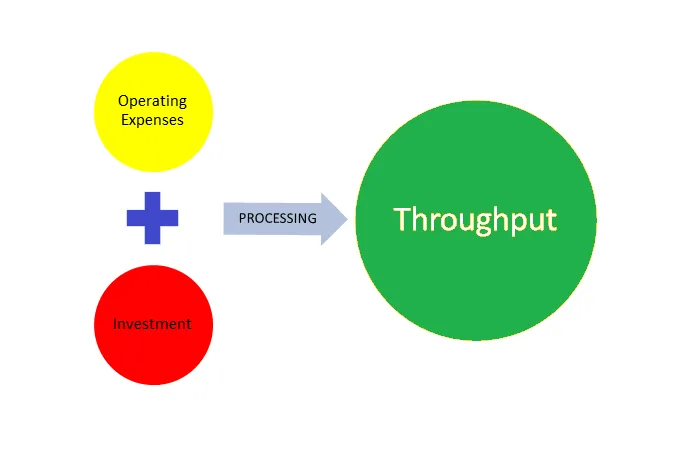
Goldratt’s ‘Throughput Accounting’ revolutionized the methods by which companies viewed their costs and associated them with profits. Unlike the traditional cost accounting methods, Goldratt argues that accounting should seek to maximize the movement of products through an organization to eliminate potential bottlenecks that prevents efficiency and speed. Goldratt argues that the current costing systems in use were developed almost a hundred years ago based upon the business practices and business designs of that particular era. The traditional accounting system therefore can be understood in the context of a “Cost World”. This cost world focuses all aspects of business value and decision making upon the cost of products themselves. In order to connect all of the subsequent aspects of business to costs, very elaborate allocation of expenses had to flow through to products. These “cost schemes” in effect have many different errors and assumptions that impacts the accuracy of accounts and Continue reading
Financial Management
Financial management entails planning for the future of a person or a business enterprise to ensure a positive cash flow, including the administration and maintenance of financial assets. The primary concern of financial management is the assessment rather than the techniques of financial quantification. Some experts refer to financial management as the science of money management. The five basic components of the Financial Management Framework are: Planning and Analysis, Asset and Liability Management, Reporting, Transaction Processing and Control.
Equity Multiplier – Meaning, Equation, and Significance
In corporate finance, understanding a company’s financial structure is crucial for assessing its risk and return potential. One of the key metrics used to evaluate the extent to which a company relies on debt to finance its assets is the equity multiplier. The equity multiplier is a financial ratio that measures the amount of financial leverage a company uses. It helps investors, analysts, and corporate managers understand how a company finances its operations through debt as opposed to equity. This ratio is important because it provides insights into a company’s risk profile and can influence key financial decisions. The equity multiplier reflects the relationship between a company’s total assets and its equity base, helping to determine the degree of financial leverage the company has. Understanding the Equity Multiplier The equity multiplier is a measure of financial leverage, which refers to the proportion of a company’s assets financed by debt as opposed Continue reading
Asset Management Ratios – Definition, Ratios, and Equations
Asset management ratios are key financial metrics that help assess how efficiently a company is utilizing its assets to generate revenue. These ratios evaluate the firm’s ability to manage its assets, such as receivables, inventory, fixed assets, and total assets, in a way that maximizes sales and operational efficiency. For businesses, efficient asset management is crucial, as it impacts both liquidity and profitability. Poor asset utilization can lead to overinvestment in unproductive assets or unnecessary costs, while effective asset management allows a company to optimize its resources and improve its overall financial performance. Most Important Asset Management Ratios 1) Receivables Turnover = Sales / Account Receivables The receivables turnover ratio measures how efficiently a company collects its accounts receivable. It indicates the number of times a company is able to convert its receivables into cash during a period (usually a year). A higher ratio implies that the company is efficiently Continue reading
Return on Equity (ROE) – Definition, Equation, and Calculation
The Return on Equity (ROE) ratio is a key financial metric used to measure a company’s profitability relative to its shareholder equity. It shows how effectively a company uses the funds invested by its shareholders to generate profit. By analyzing ROE, investors and management can assess the company’s ability to generate returns from the equity capital provided by its owners. The formula for calculating ROE is: Return on Equity = Net income after tax / Average Shareholder Equity In this formula, net income after tax represents the company’s earnings after all expenses and taxes have been deducted. Average shareholder equity is calculated by averaging the opening and closing equity balances for the period. This approach provides a more accurate measure of equity over time, reflecting fluctuations in capital. ROE expresses how much profit is earned for every dollar of equity invested, providing insight into the company’s efficiency in using shareholders’ Continue reading
Real Options in Capital Budgeting
Real options refer to a relatively new financial analytical tool that helps investors and managers to select market valuations that reflect a blend of businesses that are already known together with the value of business opportunities that are likely to arise. The Black-Scholes model is one of the best known forms of financial option theory that is applied through real options. There is need for managers and investors to understand how to take advantage of rapid changes that are occurring in economic world. This need if fulfilled by real options which gives them requisite insights into strategic investments and businesses. Real options are viable where particular conditions are met. Managers who are keen on maintaining the status quo will certainly miss the opportunities availed by this analytical tool. Economic changes occurring from time to time are a fertile breeding ground for real options. Businesses with adequate capital, reputable and intelligent Continue reading
Depreciation – Definition, Methods, and Tax Implications
Depreciation is a cost estimation method for accounting for the worth of a long-term asset over its useful life. Depreciation is used to spread the cost of a tangible asset over the accounting periods in which the asset is used. There are some questions surrounding this topic that are essential to explore. For instance, what are the tax implications of depreciation? What are the different depreciation methods, and how can they be used to calculate the amount? What are the best practices for managing depreciation? How does depreciation help to ensure a company’s financial health? Each of these questions will be explored in more detail to understand the concept of depreciation fully. Since antiquity, depreciation has been utilized for cost apportionment. Initially, the idea was developed by the Greek philosopher Aristotle, who believed that the value of an asset declined over time. By the 19th century, Italian economist Vilfredo Pareto Continue reading